U.S. industrial revitalization will require sustained investment in workforce training and advanced technologies to build new collar skills and strengthen global competitiveness. It also depends on rebuilding a full manufacturing ecosystem—from raw materials to finished goods—supported by suppliers and intermediaries at every stage.
This installment explores how innovators and manufacturing leaders are addressing today’s challenges through automation, robots, machining, AI, additive manufacturing and digital tools. These themes will take center stage at the 2026 International Manufacturing Technology Show (IMTS), held Sept. 14-19, 2026, at McCormick Place in Chicago. As a long-time participant, I look forward to engaging with the ideas and technologies shaping the industry’s comeback.
The Challenges
Manufacturers face a persistent shortage of skilled workers driven by an aging workforce, reduced migration, and a mismatch between available skills and industry needs. Negative perceptions of manufacturing careers and a tight labor market further complicate recruitment.
At the same time, demand is rising for highly skilled workers capable of operating advanced technologies. According to the Reshoring Initiative’s 2025 Reshoring Survey, workforce quality and availability rank as the top factors influencing reshoring decisions. Talent attraction and retention is cited by 65% of manufacturers as their primary challenge.
During the “Peak 65” surge from 2025-2027, when approximately 1.8 million manufacturing workers are expected to reach retirement age, manufacturers risk losing decades of institutional knowledge faster than it can be replaced. Companies must implement structured knowledge transfer strategies to preserve expertise, including mentorship programs and formal documentation processes.
Clearing the Barriers
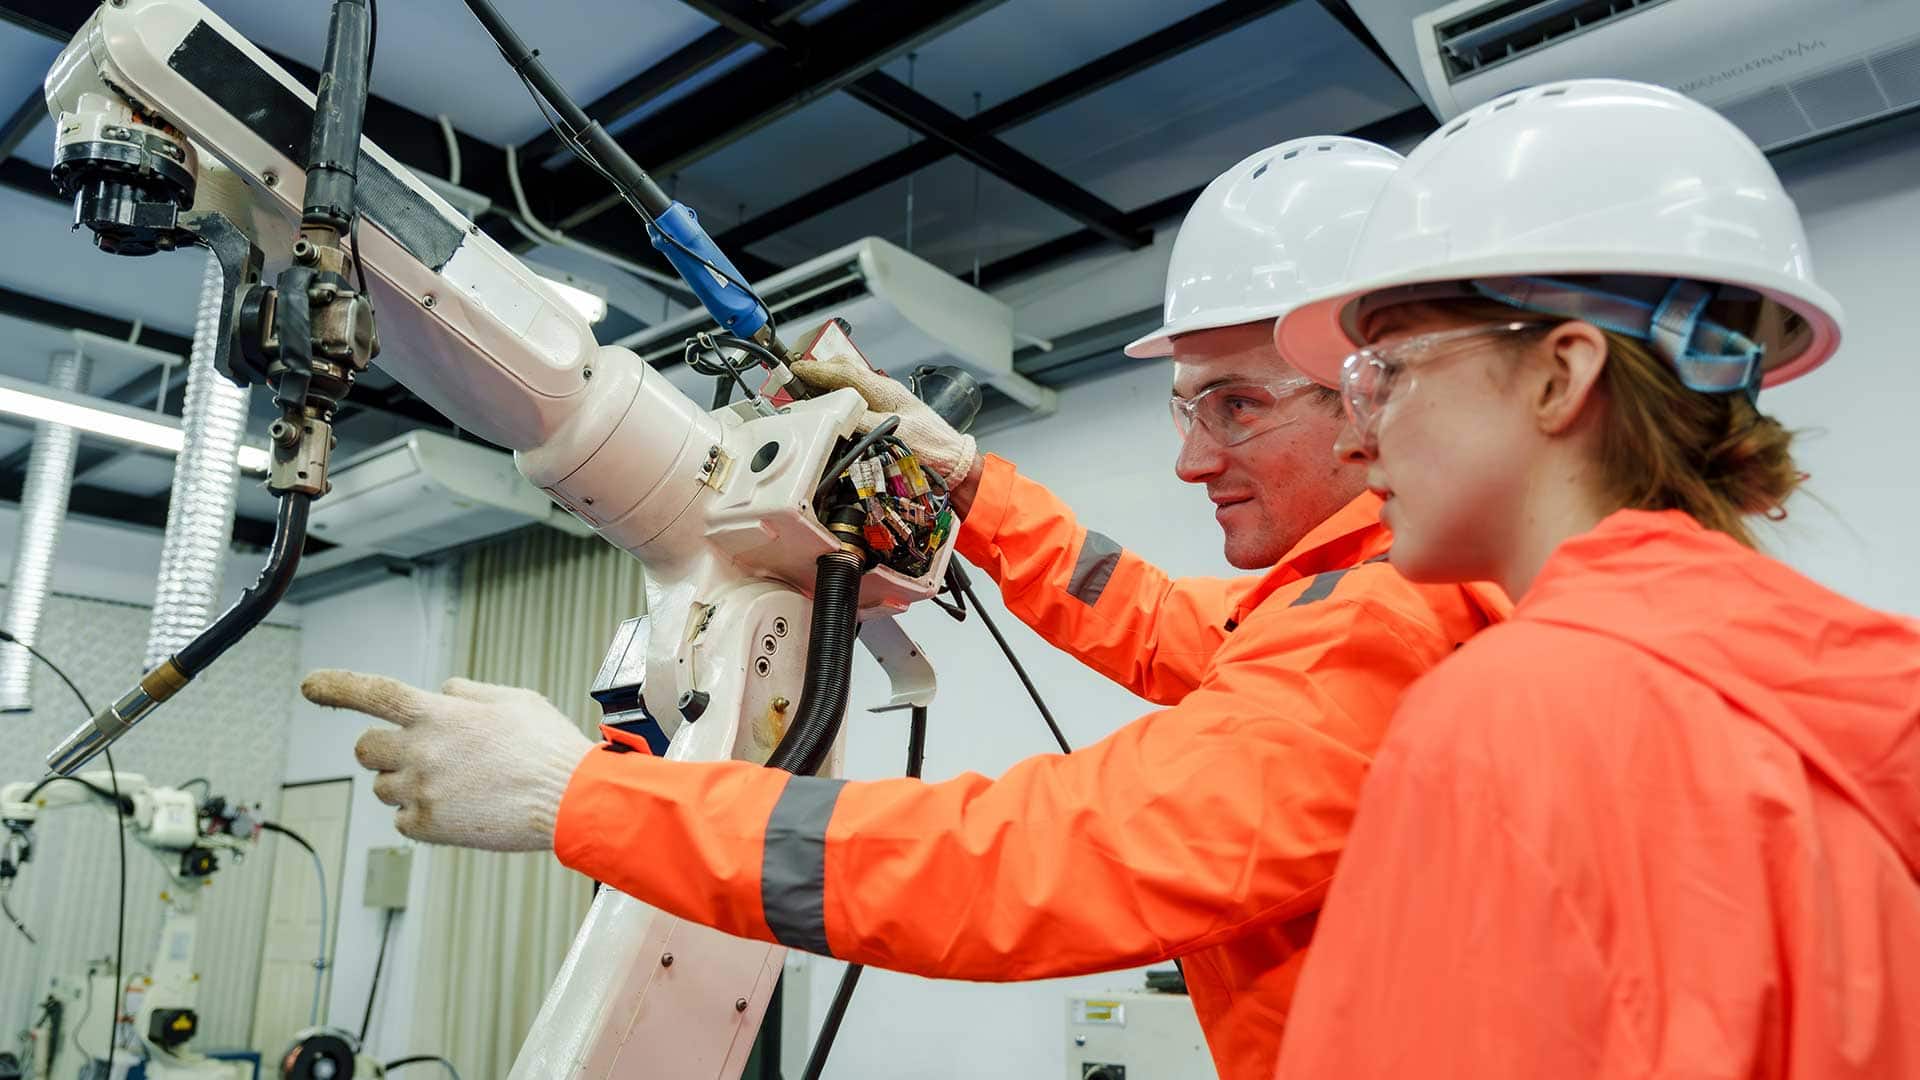
To address both the skills gap and knowledge loss, manufacturers are rethinking education and training. Initiatives such as the Smartforce Student Summit at IMTS 2026 expose students and educators to cutting-edge technologies and career pathways. These programs emphasize new roles that blend technical and digital skills, preparing workers to program and operate automated systems.
Apprenticeships are also critical. By combining classroom learning with hands-on experience, they create practical pathways into high-tech manufacturing careers while helping employers build a reliable talent pipeline.
Automation and Competitiveness
Automation is central to restoring U.S. manufacturing competitiveness and accelerating reshoring. By reducing labor costs and improving efficiency, advanced technologies allow domestic producers to compete with offshore alternatives.
The two 2025 National Metalworking Reshoring Award winners, GE Appliance and Marlin Steel, each reshored using the benefits of automation. Both companies have leveraged automation, engineering and quality improvements to bring production back to the U.S., even for high-volume, price-sensitive products. These cases demonstrate how technology can strengthen supply chains while supporting domestic growth.
The Reshoring Trend
The Reshoring Initiative tracks reshoring and foreign direct investment (FDI). The annual totals of the two trends have grown from 11,000 jobs/year in 2010 to 244,000/year in 2025. Figures from Q1 2026 project a substantial further increase this year.
America’s Top States—2025
The southern U.S. remains the most competitive reshoring and FDI region with 61% of reshoring and FDI jobs. Favorable costs, infrastructure, an established ecosystem for hot products, incentives and right-to-work make the South, stretching to Arizona, the leading region. The Midwest is second (19%), followed by the West (14%) and, finally, the Northeast (6%). Local and state incentives are often enough to impact the selection of a specific city or county. Typically, only national incentives are enough to make the U.S. competitive vs. China and other offshore competitors.
In 2025, Texas was a strong No. 1 with 14% of the jobs, followed by North Carolina and Georgia. Seven of the top 10 states are in the South, which has the statistical advantage of including the most states, 18. Michigan was the highest ranked Midwest state at No. 5. California led the West at No. 10.
Pennsylvania led the Northeast at No. 12. Some of the ranking strength comes from the leading states’ relative size, depth, workforce size and proximity to other states with large industrial and consumer markets. If we ranked based on reshoring as a percentage of population or industrial output, some small or mid-level states would rank moderately higher. Puerto Rico is recovering as pharmaceutical shifts production back to the U.S.
The Trend
Comparing 2025 to 2024, not much changed. Texas stayed No. 1. Louisiana moved up from No. 24 to No. 8, Alabama from No. 23 to No. 11 and Pennsylvania from No. 16 to No. 12. Mississippi, New York and Florida dropped out of the top 15.
Generally, changes in ranking are due to a state getting or not getting a few massive projects which each provide thousands of jobs, including supply chain jobs.
Comparing 2025 to the longer-term trend of 2010 through Q1 2026, Texas and North Carolina are No. 1 and No. 2, respectively, on both lists. Arizona dropped from No. 12 to No. 16 after a strong 2022 and 2023 driven by chip projects; Indiana from No. 13 to No. 18; and Illinois from No. 15 to No. 19.
From 2010 to 2020, the trend was driven by companies recognizing that their bets on offshoring were not paying off as expected. A study by Ohio State University Professor John Gray documented the phenomenon. Gray studied four companies that had offshored and, within a few years, reshored. The companies offshored due to the huge attraction of low wages and low prices. They reshored because all of the other costs and risks, once understood, offset those savings. We would say that the companies shifted their sourcing metric from one factor, price, to considering more of the 29 total cost of ownership (TCO) factors.
From 2020 to 2022, COVID—and the resulting recognition of corporate and national lack of self-sufficiency—drove country and companies to produce more here. In 2022 and 2023, President Joe Biden’s subsidies for chips and EV batteries drove reshoring and FDI. Battery plants chose the South, plus locations near Midwestern auto assembly plants, that would be the customers for the batteries. Chips had fewer geographic constraints and spread west to Arizona and north to Ohio and New York.
More recently, hotter industries each show a pattern. Rare-earth minerals processing is located near deposits, generally away from heavily populated regions. Pharma has typically chosen the Southeast, plus Pennsylvania and New Jersey and some Midwest and Texas. Drones are well distributed, often at startups. Data center electronics are often in the South and West.
Charting the Course
U.S. manufacturing is at a pivotal moment. Companies are navigating uncertainty with new strategies that combine workforce development, capital investment and advanced technologies. IMTS and FABTECH offer platforms to explore these solutions, connect with industry leaders and evaluate tools that can improve productivity and competitiveness.
Ready to Reshore?
Are you thinking about reshoring? Ready to narrow the cost gap and reshore? Click here to access the full list of reshoring resources offered by the Reshoring Initiative. For help, contact me at 847-867-1144 or harry.moser@reshorenow.org.
This article was originally published by Advanced Manufacturing and was republished with permission from The Reshoring Initiative.